by John McCarthy Consulting Ltd. | Nov 1, 2026 | Blog, News
Accountancy firms focus a lot on the threat of money laundering, when dealing with clients, but there is another threat that is much more insidious and more difficult to detect and prevent, and that is terrorist financing. The prevention of terrorist financing is known as counter-terrorist financing or ‘CFT’.
Terrorist financing does not necessarily involve the proceeds of crime and in fact the funds used may come from legitimate sources such as salaries, businesses, charities, donations or personal savings. Transactions may appear routine and involve relatively small amounts.
Ireland’s 2026 National Risk Assessment in Ireland (2026 NRA) highlights the importance of this issue for the accountancy sector.
Accounting firms (known in the NRA as Accountancy Service Providers) are assessed as having a significant terrorist financing risk, while Trust and Company Service Providers (TCSPs) supervised by accountancy bodies are assessed as having a moderate risk.
The Financial Action Task Force (FATF) in its July 2025 report noted that terrorist entities are reported as increasingly using professional enablers such as accountants to facilitate their financing networks.
Accountants must remain alert to indicators that may suggest funds are being used to support terrorist individuals, organisations or activities. The warning signs include (in no particular order and please note this is not an exhaustive list):
- Unexplained links to jurisdictions affected by terrorism, conflict or extremism;
- Business activities and relationships involving countries with known terrorism links or persons subject to international sanctions;
- Financial activity that is inconsistent with a client’s stated business activities Unexplained fundraising activities or collections of funds;
- Charities or non-profit organisations operating cross-border, in high-risk regions or in conflict zones (which are often simultaneously areas of humanitarian crisis) lacking adequate oversight or transparency regarding the ultimate beneficiaries of funds;
- Charities or non-profit organisations that lack formal governance, financial management, financial control, and risk management frameworks;
- Corporate structures and complex intermediary relationships that obscure links to terrorist financing and/or sanctioned individuals or entities; and
- Client’s business operating with limited staff despite high transaction volumes.
The presence of one or more of these indicators should prompt further enquiry and consideration as part of the firm’s risk-based approach to AML/CFT compliance when on-boarding new clients or carrying out periodic updating reviews on existing clients.
It’s now also expected that all new clients being onboarded and existing client subject to updated AML reviews undergo sanctions checks under the latest CCAB AML Guidance for the Accountancy Sector updated in July 2026.
See our full range of updated letter of engagement templates, now including a paragraph dealing with the use of artificial intelligence, visit our online store here.
For those of you still in the process of ISQM 1 implementation, please see our ISQM TOOLKIT or if you prefer to chat through the different audit risks and potential appropriate responses presented by this new standard, please call or e-mail John McCarthy FCA or e-mail him at john@jmcc.ie.
We typically tailor ISQM training and brainstorming sessions to suit each firm’s unique requirements.
Publications:
- The ISQM TOOLKIT 2022 is available to purchase here.
- To ensure your letters of engagement and similar templates are up to date visit our site here where immediate downloads are available in Word format. A bulk discount is available for orders of five or more items if bought together.
by John McCarthy Consulting Ltd. | Nov 1, 2026 | Blog, News
Yes, you read that right! As a reaction to UK Government plans to raise the audit exemption threshold to allow UK ‘medium-size’ companies claim audit exemption, it’s possible that the Irish Government may raise the Irish audit exemption threshold to €50m (the current RoI ‘medium-size’ company threshold).
The UK Government is currently consulting on raising the UK ‘medium size’ turnover threshold to £54m. There are other criteria to be fulfilled to qualify as a ‘medium’ company, but for the purpose of this blog, we are focusing on the headline turnover number.
Please note that this is pure speculation on our part, but stranger things have happened in the past. Would the Irish Government like to see ‘medium’ companies incorporated in the RoI start migrating to Belfast to claim the new audit exemption threshold there? Most likely not.
The UK consultation is called Modernising Corporate Reporting and was launched on 7 September 2026. It runs until 30 November 2026.
It is part of a wider overhaul of corporate reporting rules designed to cut red tape for businesses. According to a recent Financial Times report, 40,000 UK businesses would be entitled to avail of the new exemption threshold, if introduced.
See our full range of updated letter of engagement templates, now including a paragraph dealing with the use of artificial intelligence, visit our online store here.
For those of you still in the process of ISQM 1 implementation, please see our ISQM TOOLKIT or if you prefer to chat through the different audit risks and potential appropriate responses presented by this new standard, please call or e-mail John McCarthy FCA or e-mail him at john@jmcc.ie.
We typically tailor ISQM training and brainstorming sessions to suit each firm’s unique requirements.
Publications:
- The ISQM TOOLKIT 2022 is available to purchase here.
- To ensure your letters of engagement and similar templates are up to date visit our site here where immediate downloads are available in Word format. A bulk discount is available for orders of five or more items if bought together.
by John McCarthy Consulting Ltd. | Oct 27, 2026 | Blog, News
Higher risk clients trigger additional AML scrutiny by accountants. This additional AML documentation that one is supposed to have on file is known as ‘Enhanced Due Diligence’ (EDD) and the top 10 most important Due Diligence steps to take are as follows:
- Additional background checks: These checks are accompanied by a more in-depth investigation into the customer’s background, including sanctions checks.
- Source of funds and wealth: Investigate the funds to be used throughout the business relationship and the client’s total wealth, supported with documentary evidence, ideally sourced from independent credible sources.
- Independent verification: Seek independent verification of the customer’s identity documents and establish the integrity of any other supporting information provided.
- Increased monitoring: Increase the frequency and intensity of transaction monitoring to detect any suspicious activity as soon as possible.
- Third party validation: Obtain information from third party sources, such as credit reference agencies to verify the customer’s information and help better assess the risk.
- Obtain senior management approval: Where the client is a Politically Exposed Person (PEPs) as well as reviewing the latest sanctions lists. It’s expected that certain city and county councillors will become PEPs in forthcoming Government AML legislation. It is important for senior management to understand the risk that the accountancy firm undertakes.
- Limiting transactions: In certain circumstances, restrict the type and size of transactions the customer can conduct, or limit their access to certain services that the firm provides.
- Incoming funds: Require that the initial funds and the first transaction be conducted through a reputable financial institution which will attract more intensive AML supervision.
- Ongoing customer reviews: Increase the frequency of subsequent customer reviews to monthly instead of annually.
- In extreme cases: Choose to refuse the business with the customer if the risk of money laundering is too high and beyond your firm’s risk appetite.
After completing all of the above steps, each firm needs to assess, on an ongoing basis, whether it is really worthwhile dealing with such clients, given the costs of getting the AML risk assessment wrong, versus the benefits of being involved in such transactions.
For those of you still in the process of ISQM 1 implementation, please see our ISQM TOOLKIT or if you prefer to chat through the different audit risks and potential appropriate responses presented by this new standard, please call or e-mail John McCarthy FCA or e-mail him at john@jmcc.ie.
We typically tailor ISQM training and brainstorming sessions to suit each firm’s unique requirements.
Publications:
- The ISQM TOOLKIT 2022 is available to purchase here.
- To ensure your letters of engagement and similar templates are up to date visit our site here where immediate downloads are available in Word format. A bulk discount is available for orders of five or more items if bought together.
Recently the CCAB has created an AI Hub which pools together helpful resources for professional accountants in relation to AI and Ethics, created by Member bodies including the ACCA and the Chartered Accountants Ireland.
The hub contains:
- a range of guidance and checklists about AI;
- a podcast series of ethical leadership issues discussing the use of AI by the profession;
- a Statement to the Profession on the Ethical Use of Artificial Intelligence; and
- six case studies covering a range of fictional scenarios which professional accountants are likely to encounter and use in their work, including specifically for those in practice:
- AI in collecting audit evidence; and
- Using synthetic client data for LLM training in a large firm.
All the templates on our website have had a refresh as of June 2026 and the letters of engagement have had a new paragraph added for the potential use of artificial intelligence and machine learning on client assignments along with auto enrolment for payroll assignments. There is a bulk discount (five templates for the price of four) for purchases of five or more templates when purchased in a single transaction.
If you need an up-to-date engagement letter, there is a search bar near the bottom of our home page (www.jmcc.ie) to quickly look up the item you need. More details see here.
For those of you still in the process of ISQM 1 implementation, please see our ISQM TOOLKIT or if you prefer to chat through the different audit risks and potential appropriate responses presented by this new standard, please call or e-mail John McCarthy FCA or e-mail him at john@jmcc.ie.
We typically tailor our training and brainstorming sessions to suit each firm’s unique requirements.
Publications:
by John McCarthy Consulting Ltd. | Oct 7, 2026 | Blog, News
The CCAB is the representative body for the five accounting bodies in the British Isles which include 285,000 accounts in the UK and Ireland.
Recently the CCAB has created an AI Hub which pools together helpful resources for professional accountants in relation to AI and Ethics, created by Member bodies including the ACCA and the Chartered Accountants Ireland.
The hub contains:
- a range of guidance and checklists about AI;
- a podcast series of ethical leadership issues discussing the use of AI by the profession;
- a Statement to the Profession on the Ethical Use of Artificial Intelligence; and
- six case studies covering a range of fictional scenarios which professional accountants are likely to encounter and use in their work, including specifically for those in practice:
- AI in collecting audit evidence; and
- Using synthetic client data for LLM training in a large firm.
All the templates on our website have had a refresh as of June 2026 and the letters of engagement have had a new paragraph added for the potential use of artificial intelligence and machine learning on client assignments along with auto enrolment for payroll assignments. There is a bulk discount (five templates for the price of four) for purchases of five or more templates when purchased in a single transaction.
If you need an up-to-date engagement letter, there is a search bar near the bottom of our home page (www.jmcc.ie) to quickly look up the item you need. More details see here.
For those of you still in the process of ISQM 1 implementation, please see our ISQM TOOLKIT or if you prefer to chat through the different audit risks and potential appropriate responses presented by this new standard, please call or e-mail John McCarthy FCA or e-mail him at john@jmcc.ie.
We typically tailor our training and brainstorming sessions to suit each firm’s unique requirements.
Publications:
by John McCarthy Consulting Ltd. | Oct 6, 2026 | Blog, News
The CCAB issued updated AML Guidance for members in July 2026. The word ‘sanction’ or ‘sanctions’ or ‘sanctioned’ now appears 131 times, compared to 23 times in the last version in published in 2022. Suffice to say that verifying the sanctions status of clients is now an important features of AML client due diligence (CDD)
Ireland does not implement an autonomous sanctions regime of its own but enacts legislation for both UN and EU sanctions and embargoes.
Sanctions (according to the website of the website of the Department of Enterprise Tourism and Employment) are also referred to as ‘restrictive measures’ are legally binding measures that can be taken against individuals, entities or countries. Sanctions are adopted by the United Nations Security Council under Chapter VII of the UN Charter, and through decisions taken at European Union level.
UN sanctions
Information on UN sanctions from their 14 UN sanctions committees may be found on the UN sanctions website. The UN also publishes a consolidated list of individuals and entities subject to sanctions imposed by the UN Security Council.
EU sanctions
Summaries of all EU sanctions regimes are available on the EU Sanctions Map website.
All the templates on our website have had a refresh as of June 2026 and the letters of engagement have had a new paragraph added for the potential use of artificial intelligence and machine learning on client assignments along with auto enrolment for payroll assignments. There is a bulk discount (five templates for the price of four) for purchases of five or more templates when purchased in a single transaction.
If you need an up-to-date engagement letter, there is a search bar near the bottom of our home page (www.jmcc.ie) to quickly look up the item you need. More details see here.
For those of you still in the process of ISQM 1 implementation, please see our ISQM TOOLKIT or if you prefer to chat through the different audit risks and potential appropriate responses presented by this new standard, please call or e-mail John McCarthy FCA or e-mail him at john@jmcc.ie.
We typically tailor our training and brainstorming sessions to suit each firm’s unique requirements.
Publications:
by John McCarthy Consulting Ltd. | Sep 25, 2026 | Blog, News
There has been a lot written about the new FRS 102 which came into force this year, but readers may be unclear as to which version they are supposed to be using. The amendments in the standard are collectively known as the Periodic Review Amendments 2024 (published in March 2024, the date when the new version was finalised for publication). Most of the changes are in the leasing (section 20) and revenue recognition (section 23) sections.
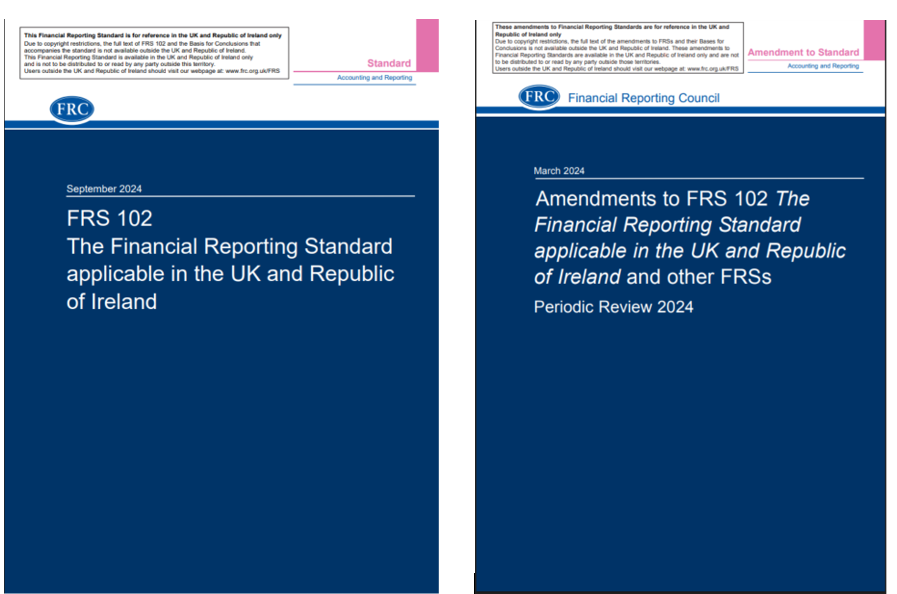
The latest version of FRS 102 ‘The Financial Reporting Standard applicable in the UK and Republic of Ireland’ is now fully in force for accounting periods that began on/after 1 January 2026. It was published in September 2024. Early application was permitted provided all the amendments were applied together.
There was an exception for supplier finance arrangement disclosure requirements (dealt with in paragraphs 7.20B and 7.20C), which were effective for accounting periods beginning on or after 1 January 2025, with earlier application also permitted.
However, which version are you supposed to be using right now?
Correct version – the ‘clean’ version
The correct version of FRS 102 to use is the September 2024 version available here. This is the final, clean’, version with no tracked changes. Unfortunately, the Financial Reporting Council no longer publishes a printed book version of the standard.
Some minor amendments were made in February 2026 relating principally to entities which choose to adapt one of the balance sheet formats and/or one of the profit and loss account formats, as a result of the replacement of IAS 1 Presentation of Financial Statements with IFRS 18 Presentation and Disclosure in Financial Statements. Minor clarifications are also made in respect of the Periodic Review 2024 amendments
There was a minor March 2025 amendment to do with a change in UK company size thresholds.
Also useful – the ‘tracked changes’ version
For the nerds who like to know precisely what the changes are, you need to use the March 2024 version, which is available here. The official title is ‘Amendments to FRS 102 The Financial Reporting Standard applicable in the UK and Republic of Ireland and other FRSs Periodic Review 2024’.
It has a:
- strike through for the parts of the previous standard that have been removed and
an underline under the text that has been added.
All the templates on our website have had a refresh as of June 2026 and the letters of engagement have had a new paragraph added for the potential use of artificial intelligence and machine learning on client assignments along with auto enrolment for payroll assignments. There is a bulk discount (five templates for the price of four) for purchases of five or more templates when purchased in a single transaction.
If you need an up-to-date engagement letter, there is a search bar near the bottom of our home page (www.jmcc.ie) to quickly look up the item you need. More details see here.
For those of you still in the process of ISQM 1 implementation, please see our ISQM TOOLKIT or if you prefer to chat through the different audit risks and potential appropriate responses presented by this new standard, please call or e-mail John McCarthy FCA or e-mail him at john@jmcc.ie.
We typically tailor our training and brainstorming sessions to suit each firm’s unique requirements.
Publications: