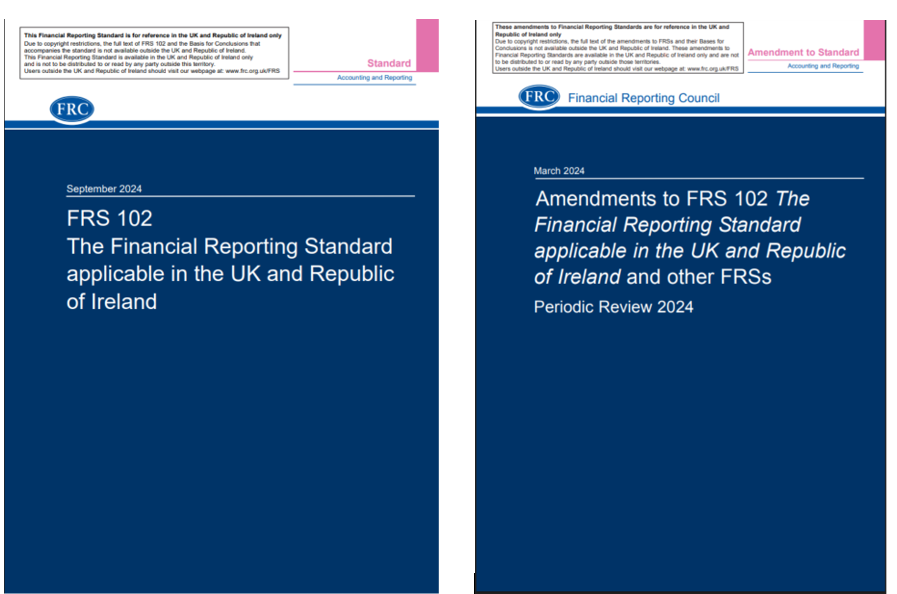
There has been a lot written about the new FRS 102 which came into force this year, but readers may be unclear as to which version they are supposed to be using. The amendments in the standard are collectively known as the Periodic Review Amendments 2024 (published in March 2024, the date when the new version was finalised for publication). Most of the changes are in the leasing (section 20) and revenue recognition (section 23) sections.
The latest version of FRS 102 ‘The Financial Reporting Standard applicable in the UK and Republic of Ireland’ is now fully in force for accounting periods that began on/after 1 January 2026. It was published in September 2024. Early application was permitted provided all the amendments were applied together.
There was an exception for supplier finance arrangement disclosure requirements (dealt with in paragraphs 7.20B and 7.20C), which were effective for accounting periods beginning on or after 1 January 2025, with earlier application also permitted.
However, which version are you supposed to be using right now?
Correct version – the ‘clean’ version
The correct version of FRS 102 to use is the September 2024 version available here. This is the final, clean’, version with no tracked changes. Unfortunately, the Financial Reporting Council no longer publishes a printed book version of the standard.
Some minor amendments were made in February 2026 relating principally to entities which choose to adapt one of the balance sheet formats and/or one of the profit and loss account formats, as a result of the replacement of IAS 1 Presentation of Financial Statements with IFRS 18 Presentation and Disclosure in Financial Statements. Minor clarifications are also made in respect of the Periodic Review 2024 amendments
There was a minor March 2025 amendment to do with a change in UK company size thresholds.
Also useful – the ‘tracked changes’ version
For the nerds who like to know precisely what the changes are, you need to use the March 2024 version, which is available here. The official title is ‘Amendments to FRS 102 The Financial Reporting Standard applicable in the UK and Republic of Ireland and other FRSs Periodic Review 2024’.
It has a:
- strike through for the parts of the previous standard that have been removed and
an underline under the text that has been added.
All the templates on our website have had a refresh as of June 2026 and the letters of engagement have had a new paragraph added for the potential use of artificial intelligence and machine learning on client assignments along with auto enrolment for payroll assignments. There is a bulk discount (five templates for the price of four) for purchases of five or more templates when purchased in a single transaction.
If you need an up-to-date engagement letter, there is a search bar near the bottom of our home page (www.jmcc.ie) to quickly look up the item you need. More details see here.
For those of you still in the process of ISQM 1 implementation, please see our ISQM TOOLKIT or if you prefer to chat through the different audit risks and potential appropriate responses presented by this new standard, please call or e-mail John McCarthy FCA or e-mail him at john@jmcc.ie.
We typically tailor our training and brainstorming sessions to suit each firm’s unique requirements.
Publications:
-
- The ISQM TOOLKIT 2022 is available to purchase here.
- See our latest Anti-Money Laundering Policies Controls & Procedures Manual (March 2022) – View the Table of Contents click here.
- To ensure your letters of engagement and similar templates are up to date visit our site here where immediate downloads are available in Word format. A bulk discount is available for orders of five or more items if bought together