by John McCarthy Consulting Ltd. | Jul 3, 2026 | Blog, News
This is part two of our blog on Going Concern for SMEs. Last week we highlighted the fact that the ACCA have recently (April 2026) issued a Technical Factsheet to assist small and medium entities and their advisor firms to comply with the requirements of FRS 102. The Factsheet is called ‘Going concern for SMEs’.
The Factsheet provides some examples of going concern scenarios to consider along with a very useful table of with a non-exhaustive list of examples of material uncertainties related to going concern for Directors and their advisers to consider:
| Issue |
Reason why it is a going concern |
| The balance sheet shows a net current liabilities (or net liabilities) position |
This indicates the entity may be unable to meet debts as they fall due |
| The bank does not renew borrowing facilities |
A lack of cash makes it difficult for a company to pay suppliers, employees and other liabilities as they fall due |
| The company has breached a loan agreement |
Breaches of a loan agreement may trigger immediate repayment, hence placing additional pressure on the cash flow of the business |
| Staff are not paid on time |
This indicates a lack of working capital and potential loss of employee goodwill |
| Legal claims have been brought against the entity |
If successful, these may result in significant cash outflows, thus placing additional pressure on working capital |
| Loss of key staff |
This may make it difficult for the entity to trade |
| Changes in laws and regulations |
Such changes may make it costlier for the business to comply, and the costs of compliance may be more than the company can realistically afford |
| Changes in laws and regulations |
Such changes may make it costlier for the business to comply, and the costs of compliance may be more than the company can realistically afford |
| Failure to obtain credit from suppliers |
This indicates a bad credit rating, which usually arises from a failure to pay liabilities |
| Missing payments to HMRC or an equivalent taxation authority |
Payments to HMRC or an alternative tax authority should be prioritised, and any missed payments may indicate the company has a lack of working capital |
| Negative cash flows |
This indicates overtrading |
All the templates on our website have had a refresh as of June 2026 and the letters of engagement have had a new paragraph added for the potential use of artificial intelligence and machine learning on client assignments along with auto enrolment for payroll assignments. There is a bulk discount (five templates for the price of four) for purchases of five or more templates when purchased in a single transaction.
If you need an up-to-date engagement letter, there is a search bar near the bottom of our home page (www.jmcc.ie) to quickly look up the item you need. More details see here.
For those of you still in the process of ISQM 1 implementation, please see our ISQM TOOLKIT or if you prefer to chat through the different audit risks and potential appropriate responses presented by this new standard, please call or e-mail John McCarthy FCA or e-mail him at john@jmcc.ie.
We typically tailor our training and brainstorming sessions to suit each firm’s unique requirements.
Publications:
by John McCarthy Consulting Ltd. | Jul 3, 2026 | Blog, News
The ACCA have recently (April 2026) issued a Technical Factsheet to assist small and medium entities and their advisor firms to comply with the requirements of FRS 102. The Factsheet is called ‘Going concern for SMEs’.
The Financial Reporting Council (FRC) have already issued their own guidance on going concern but it does not cater for small and micro-entities. So the ACCA are filling the gap.
The Factsheet points out that all companies (including those that are audit exempt) are obliged to carry out an assessment of their ability to continue in operational existence for the foreseeable future. The term ‘foreseeable future’ is not defined in accounting standards but is taken to mean at least (but not limited to) 12 months from the date of approval of the financial statements.
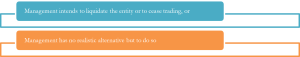
There are only two circumstances in which an entity does not prepare financial statements on a going concern basis:
When carrying out its assessment of going concern, management is required to take into account all relevant facts and circumstances at the date of approval of the financial statements.
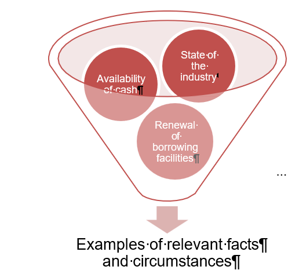
‘Relevant facts and circumstances’ may need careful thought, for example these three important criteria (which are not a complete list of variables to consider):
- Availability of cash
- State of the industry
- Renewal of borrowing facilities
Several other indicators will also be needed by Directors to make their going concern assessment including (bit not an exhaustive list):
- budgets and forecasts;
- interim management information (e.g. management accounts);
- likelihood of borrowing facilities (e.g. overdrafts) being renewed;
- current headroom with borrowing facilities;
- overall state of the market in which the company operates;
- potential impact of any ongoing litigation claims or potential outcome of contingent liabilities; and
- support available from a group (e.g. a parent entity).
More on this topic next week.
All the templates on our website have had a refresh as of June 2026 and the letters of engagement have had a new paragraph added for the potential use of artificial intelligence and machine learning on client assignments along with auto enrolment for payroll assignments. There is a bulk discount (five templates for the price of four) for purchases of five or more templates when purchased in a single transaction.
If you need an up-to-date engagement letter, there is a search bar near the bottom of our home page (www.jmcc.ie) to quickly look up the item you need. More details see here.
For those of you still in the process of ISQM 1 implementation, please see our ISQM TOOLKIT or if you prefer to chat through the different audit risks and potential appropriate responses presented by this new standard, please call or e-mail John McCarthy FCA or e-mail him at john@jmcc.ie.
We typically tailor our training and brainstorming sessions to suit each firm’s unique requirements.
Publications:
by John McCarthy Consulting Ltd. | Jun 18, 2026 | Blog, News
The ISQM 1 regime is now fully in place since its initial roll out in 2021. Every Irish audit firm will need an ISQM-compliant System of Quality Management (‘SOQM’).
Many firms have already prepared their ISQM 1 policy statement (called the Statement of Quality Management or SoQM), but have you reviewed yours in accordance with the standard on an annual basis since its initial implementation.
Our ISQM TOOLKIT is the answer to your needs and is available to purchase now for immediate download to help you. Click here for more details.
Regulators are looking for clear evidence of progress with the application of the standard and especially with evidence of root cause analysis (RCA).
Here are our top ten tips to helping you get your SOQM across the finish line:
- Read the ISQM. There’s really no way around this!
We’d recommend you also get hold of the IAASM Implementation Guide, which is genuinely helpful – although be warned; this is for the international version of the ISQM and doesn’t include the additional quality responses added to the Irish standard by the Irish Audit & Accounting Supervisory Authority (IAASA).
- Assess your current approach to audit quality. Firms have various audit quality policies and procedures already in place. While we want to stress that you shouldn’t simply ‘bolt on’ ISQM to your existing approach, it’s helpful to get a clear insight into what’s happening now (e.g., by taking a look with a critical eye at your existing procedures and matching them to the requirements of our ISQM Toolkit).
This may mean gathering various documents (like staff appraisals, CPD plans and IES 8), clarifying existing arrangements with the rest of the audit team and organising your thoughts.
- Find out what your team thinks about your current approach. Chances are, you and your team already have sound insights into what’s working well and what isn’t, and some honest feedback may be painful but is essential to making progress.
John McCarthy Consulting Ltd. (working in conjunction with our colleagues in Apex Professional Consulting Ltd.) has produced the ISQM TOOLKIT for the Republic of Ireland. It comes with a unique team questionnaire that can help you to gather anonymous feedback including suggestions for tackling problem areas.
- Start with leadership and governance issues. For most if not all small firms, a critical success factor for ISQM compliance is the degree of support from partners, especially managing partners within firms.
Whether your firm is a sole practitioner or a larger firm, ISQM 1 challenges senior leadership to demonstrate genuine commitment to audit quality, recognising that this may not always align with a firm’s commercial strategy or its leaders’ priorities. You need to identify and deal with those conflicts, if present. You’ll also need to consider how much of the SOQM can be delegated to others and how the firm’s leadership will demonstrate that they bear ultimate responsibility for its success.
5. Don’t dismiss the appointment stage. Many firms assign consideration of (re)appointment to junior audit staff who lack the judgement to assess ethical threats and to apply the right safeguards. Accepting a client relationship or engagement inappropriately removes any chance to achieve a quality audit.
6. Be honest about priorities. Many firms say that they’re committed to audit quality, but a cursory scrutiny about how much of the firm’s time and money is spent in supporting and developing high quality audit may suggest otherwise. ISQM 1 demands that firms allocate enough resource to recruit and develop audit teams, supply them with appropriate tools (including hardware and software) and allow them the time to conduct audits thoroughly. You’ll also need to assess the quality risks of over-relying on external training providers, file reviewers or providers of methodology or IT tools.
7. Refocus on prevention rather than cure. In the past, many audit firms have relied on regular cold file reviews to ensure their quality is up to scratch. Whilst such reviews will still play a key role, firms need to consider how to avoid audit defects altogether. For many audit partners, this may mean reducing the amount of time spent in review, and increasing the time spent in directing and supervising audits whilst in progress. Better prepared and managed teams should produce better audit files that need less review and remediation.
8. Plan your monitoring as you go. As you set out your SOQM, make sure that every element is trackable and assign responsibility for monitoring to specific individuals, with clear instructions about how they should check progress and how they must record this. This should make the ‘monitoring and remediation’ part of the process much less burdensome. Don’t leave it all until the end!
9. Get familiar with Root Cause Analysis (‘RCA’). This is a tool that has increased in profile of late, and while RCA can be sophisticated, it needn’t always be so. The aim is to identify systemic defects that, if corrected, will prevent problems from recurring. Don’t be afraid of asking ‘why did X happen’ multiple times when a quality problem is spotted, until the roots are uncovered.
10. Consider external support. Whilst it’s possible to implement ISQM 1 without any other support, especially if you use a good transition tool you may find that getting the assistance of a specialist can be hugely valuable, even if just as a sounding board.
If you need assistance with implementation, or have any questions please contact John by e-mail john@jmcc.ie.
The ISQM TOOLKIT is available here to purchase now for immediate download.
All the templates on our website have had a refresh as of June 2026 and the letters of engagement have had new paragraphs added for:
- the potential use of artificial intelligence and machine learning on client assignments;
- along with auto enrolment for payroll assignments.
There is a bulk discount (five templates for the price of four) for purchases of five or more templates when purchased in a single transaction.
If you need an up-to-date engagement letter, there is a search bar near the bottom of our home page (www.jmcc.ie) to quickly look up the item you need. More details see here.
For those of you still in the process of ISQM 1 implementation, please see our ISQM TOOLKIT or if you prefer to chat through the different audit risks and potential appropriate responses presented by this new standard, please call or e-mail John McCarthy FCA or e-mail him at john@jmcc.ie.
We typically tailor our training and brainstorming sessions to suit each firm’s unique requirements.
Publications:
All the templates on our website have had a refresh as of June 2026 and the letters of engagement have had new paragraphs added for:
- the potential use of artificial intelligence and machine learning on client assignments;
- along with auto enrolment for payroll assignments.
There is a bulk discount (five templates for the price of four) for purchases of five or more templates when purchased in a single transaction.
If you need an up-to-date engagement letter, there is a search bar near the bottom of our home page (www.jmcc.ie) to quickly look up the item you need. More details see here.
For those of you still in the process of reviewing your ISQM 1 implementation, please see our ISQM TOOLKIT or if you prefer to chat through the different audit risks and potential appropriate responses presented by this new standard, please call or e-mail John McCarthy FCA or e-mail him at john@jmcc.ie.
We typically tailor our training and brainstorming sessions to suit each firm’s unique requirements.
Publications:
by John McCarthy Consulting Ltd. | Jun 18, 2026 | Blog, News
Once upon a time it was possible to have the same client engagement letter in place for several years, without too much upset.
However, the pace of change in the various pieces of overlapping legislation that impact on engagement letters, seems to be getting faster and faster. Different obligations under criminal law, tax law, company law and anti-money laundering that are now required in the typical contract with your client, mean that there is a never-ending requirement to review your letters and issue revised and updated letters to your clients on an annual basis.
Here is a quick checklist of the legislation you need to include in audit engagement letters:
| Topic |
Legislation |
| Company law |
Companies Act 2014 |
| Criminal law
|
· Section 59 Criminal Justice (Theft and Fraud Offences) Act, 2001 and 2021
· Criminal Justice Act 2011 |
| Tax law |
Section 1079 Taxes Consolidation Act, 1997 |
| Anti-Money laundering/terrorist financing |
Criminal Justice (Money Laundering and Terrorist Financing) Acts, 2010 to 2021 |
| Data Protection |
Data Protections Acts 1988 to 2018 and the GDPR |
All the templates on our website have had a refresh as of June 2026 and the letters of engagement have had new paragraphs added for:
- the potential use of artificial intelligence and machine learning on client assignments;
along with auto enrolment for payroll assignments.
If you need an up-to-date engagement letter, there is a search bar near the bottom of our home page (www.jmcc.ie) to quickly look up the item you need. More details see here.
For those of you still in the process of ISQM 1 implementation, please see our ISQM TOOLKIT or if you prefer to chat through the different audit risks and potential appropriate responses presented by this new standard, please call or e-mail John McCarthy FCA or e-mail him at john@jmcc.ie.
We typically tailor our training and brainstorming sessions to suit each firm’s unique requirements.
Publications:
by John McCarthy Consulting Ltd. | Jun 18, 2026 | Blog, News
Under the code of ethics of the professional accountancy bodies, it is mandatory for accountancy practices, when taking on a new client or renewing the professional relationship with an existing client, to obtain a signed letter of engagement setting out the terms of the business agreement and contracted services. This blog highlights the top ten of engagement letter contents. More tips to follow in future blogs.
What needs to be included in a letter of engagement?
The best written letters should include the following:
- Cover letter/key facts;
- Standard terms of business/limitation of liability (except for audit work in the RoI);
- Reference to the appropriate accounting framework such as IFRS, FRS 102 or FRS 105;
- Audit;
- Accountant’s reports (i.e. for audit exempt and unincorporated entity assignments);
- ‘Agreed upon Procedures’ such as under the International Federation of Accountants ISRS 4400 where an auditor simply provides a report of the factual findings of agreed-upon procedures and where no assurance is expressed. Users of such reports assess for themselves, the procedures and findings which are reported by the auditor and draw their own conclusions from the auditor’s work;
- Accounting services e.g. accounts production, management accounting, bookkeeping;
- Taxation services;
- Other services e.g., payroll (including auto enrolment), VAT returns, company secretarial services;
- Specialist reporting assignmentsg. Central Bank requirements for insurance brokers and the Accountants’ Report to the Law Society under the Solicitors Accounts Regulations, 2023.
All the templates on our website have had a refresh as of June 2026 and the letters of engagement have had a new paragraph added for the potential use of artificial intelligence and machine learning on client assignments along with auto enrolment for payroll assignments. There is a bulk discount (five templates for the price of four) for purchases of five or more templates when purchased in a single transaction.
If you need an up-to-date engagement letter, there is a search bar near the bottom of our home page (www.jmcc.ie) to quickly look up the item you need. More details see here.
For those of you still in the process of ISQM 1 implementation, please see our ISQM TOOLKIT or if you prefer to chat through the different audit risks and potential appropriate responses presented by this new standard, please call or e-mail John McCarthy FCA or e-mail him at john@jmcc.ie.
We typically tailor our training and brainstorming sessions to suit each firm’s unique requirements.
Publications: